How to Use Automated Savings Tools to Buffer Against Emergency Expenses
Elena Rodriguez
Certified Financial Planner · Updated October 2026
Elena Rodriguez
Certified Financial Planner · Updated October 2026
Imagine it is a Tuesday morning in mid-February 2026. You are driving to work when you hear a sudden, metallic thud from beneath your car. The mechanic's estimate arrives an hour later: $1,450 for a new alternator and labor. For many, this unexpected expense triggers a cascade of stress, often leading to high-interest credit card debt or the use of a personal loan to cover the gap. However, if you had utilized automated savings tools effectively, that $1,450 might have already been sitting in a dedicated fund, waiting for exactly this moment.
The reality is that most people struggle with emergency funds not because they lack income, but because they lack a system to capture small amounts of capital before it can be spent on non-essential items. In 2026, the digital landscape offers more ways than ever to 'set and forget' your financial safety net. This article will guide you through the mechanics of automated saving, helping you decide which strategies—from micro-savings to tiered transfers—will best protect your budget without making you feel cash-strapped.
Current data suggests that nearly 60% of Americans would struggle to cover a $1,000 emergency with cash on hand. By implementing automation, you are essentially engineering your way out of this statistic. We will explore how to move from 'saving what is left at the end of the month'—which is often nothing—to 'paying yourself first' through technology.
The most unintimidating way to start an emergency fund is through micro-savings. This method relies on the principle of 'rounding up' transactions. For example, if you buy a coffee for $3.75, a round-up tool automatically transfers $0.25 from your checking account into a savings account. While these amounts seem negligible in isolation, they aggregate significantly over time.
Consider this worked example: Suppose you make roughly 40 such transactions per week. If the average round-up is $0.40, you are saving $16 per week. Over a single year, that equates to approximately $832, not including any interest earned in a high-yield account. This is the power of passive accumulation; you are building a buffer without ever having to make a conscious decision to 'save' that specific money.
To implement this effectively, follow these steps:
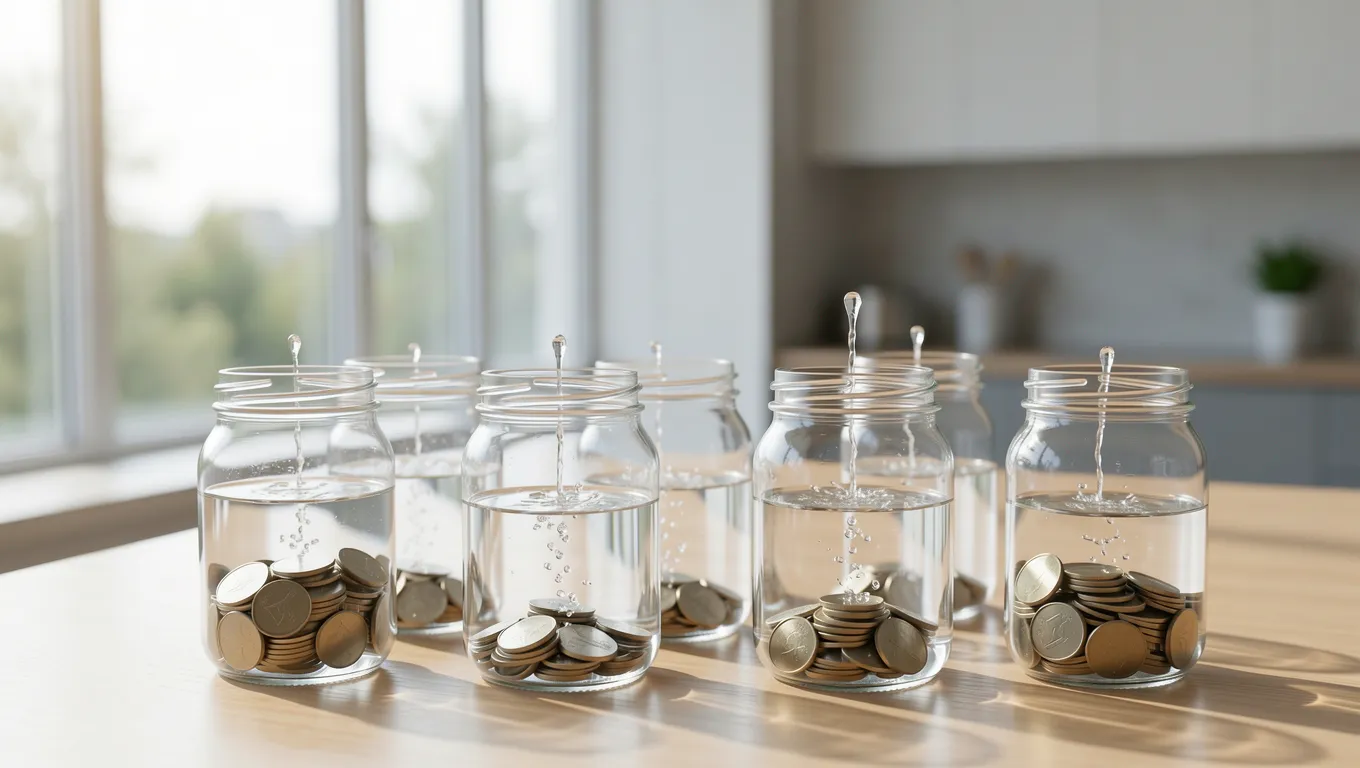
A common mistake is trying to save for every possible emergency with one giant pool of money. Instead, experts often recommend a tiered approach to automation. This involves splitting your automated transfers into different 'buckets' based on the urgency and size of the potential expense.
Level One is your 'Immediate Buffer.' This should be an amount that covers small, sudden needs like a $500 car repair or a broken appliance. You might automate a $25 weekly transfer specifically for this tier. Level Two is your 'Core Emergency Fund,' intended to cover three to six months of essential living expenses. For someone whose monthly bills total $3,000, the target goal would be between $9,000 and $18,000.
To set this up, you can schedule recurring transfers from your paycheck or your main checking account directly into different sub-accounts. For instance, if your monthly take-home pay is $4,000, you might automate a $200 transfer to Tier One and a $300 transfer to Tier Two on the day your direct deposit hits. This ensures that as you build wealth, you are simultaneously building layers of protection that serve different purposes.
When deciding where to direct your automated transfers, you must weigh the benefit of interest against the need for immediate access. This is a classic trade-off between yield and liquidity.
On one hand, a High-Yield Savings Account (HYSA) might offer an APY significantly higher than a standard checking account. For example, in 2026, you might find HYSAs offering 4.0% to 5.0% APR, while traditional checking accounts often hover near 0.01%. If you have $10,000 in an HYSA at 4.5%, you earn roughly $450 a year in interest just for letting it sit there.
On the other hand, there is the 'friction' factor. Most HYSAs are held at different institutions than your primary checking account. This means that if an emergency strikes on a Saturday night, transferring money from your HYSA back to your checking might take 1-3 business days. The trade-off is simple: higher growth for slightly slower access vs. instant access for zero growth.
A balanced strategy involves keeping one month of expenses in an easily accessible (but separate) savings account at your primary bank, while directing all subsequent automated transfers to a high-yield account at a different institution.
The greatest strength of automation—its invisibility—is also its greatest psychological pitfall. When you do not see the money leaving your account, it is easy to forget that it actually exists and is intended for a specific purpose. This can lead to 'lifestyle creep,' where you increase your discretionary spending because your checking account balance looks higher than it actually is.
To avoid this, you must practice active monitoring. Even though the transfers are automatic, you should review your savings accounts at least once a month. This prevents the money from becoming 'lost' to your consciousness. A major warning: Never automate more than you can realistically afford to lose from your checking account without notice.
Another psychological hurdle is the feeling of deprivation. Many people fail at saving because they try to automate too much, too fast. If you attempt to save 30% of your income via automation immediately, you may experience a 'rebound effect' where you overspend in other areas out of frustration. Instead, start with an amount so small that it feels insignificant—perhaps just $10 or $20 per week—and increase the amount by just 1% every two months. This gradual escalation allows your lifestyle to adjust without a sudden shock to your cash flow.
A frequent dilemma for savers is deciding whether to automate savings or accelerate debt repayment. If you have a credit card with a 24% APR, every dollar you put into a 4.5% HYSA is mathematically losing you money in the long run. In this scenario, the math favors aggressive debt repayment over building a massive buffer.
However, there is an edge case: if you have zero savings and high-interest debt, using all your cash for debt can leave you vulnerable to new debt when the next emergency hits. The most effective decision framework follows this order:
Some people use tools like personal loans to consolidate this high-interest debt. While a loan from a lender might offer a lower interest rate than a credit card, it is only a tool for stability if you have also addressed the spending habits that led to the debt in the first place. If you find yourself constantly borrowing to cover emergencies despite having an automated savings plan, it may be time to re-evaluate your entire budget rather than just your savings tools.
Not all financial emergencies are created equal, and your automation strategy should reflect that. Most people think only of 'disasters,' but many emergencies are actually 'planned-unplanned' events—things like annual car insurance premiums or holiday spending.
This is where 'sinking funds' come into play. A sinking fund is a type of automated savings designed for a specific, non-emergency expense that occurs periodically. For example, if you know your car registration costs $300 every year in October, you can set up an automated transfer of $25 per month starting in January. This prevents the 'emergency' from ever feeling like one.
Expert nuance often overlooked is the impact of inflation on cash savings. While a liquid emergency fund is essential for security, keeping too much money in a low-interest account over many years can result in a loss of purchasing power. In 2026, as economic conditions fluctuate, it is wise to ensure that your long-term 'buffer' isn't just sitting in a checking account, but is at least earning enough interest to keep pace with inflation. A well-designed system uses automation to move money from low-interest/high-liquidity accounts into higher-interest/moderate-liquidity accounts as the fund grows.